To fill out Form 8949 for cryptocurrency, identify your reportable digital asset disposals, gather the acquisition date, disposal date, proceeds, cost basis, and holding period for each transaction, and separate short-term activity from long-term activity. Choose the correct digital asset reporting box, complete columns (a) through (h), total each category, and transfer those totals to Schedule D.
You may receive Form 1099-DA for certain broker-reported digital asset sales. That form may not include every transaction or all the basis information you need, especially when assets moved between exchanges or wallets. Your own records still matter.
Multiple platforms, self-custody wallets, missing cost basis, decentralized finance activity, and non-fungible tokens can make the reconciliation harder than completing the form itself. At CMP, our cryptocurrency tax services help taxpayers organize complex digital asset records and determine how to report transactions.
First, confirm whether your cryptocurrency activity belongs on Form 8949.
What Is Form 8949, and Why Is It Important for Cryptocurrency Tax Reporting?
Form 8949 reports sales and exchanges of capital assets. For cryptocurrency investors, it generally provides transaction-level details for reportable sales, swaps, purchases made with cryptocurrency, and other dispositions of digital assets held as capital assets.
The form reconciles the amounts reported by brokers on Form 1099-DA or other statements with the amounts on your return. Schedule D then summarizes the applicable Form 8949 totals and calculates your overall capital gain or loss. Complete Form 8949 before the related Schedule D lines unless an IRS exception allows qualifying transactions to go directly on Schedule D.
Who Needs to Fill Out Form 8949 for Cryptocurrency?
You generally use Form 8949 when you dispose of cryptocurrency or an NFT that you held as a capital asset. The result can be a gain or a loss.
| Generally report on Form 8949 | Generally do not report on Form 8949 |
| Sell a digital asset for cash | Buy a digital asset with cash |
| Exchange one digital asset for another | Hold a digital asset without disposing of it |
| Use cryptocurrency to buy goods or services | Transfer assets between wallets or accounts you own |
| Sell or exchange an investment NFT | Receive mining or staking rewards before a later disposal |
Mining or staking rewards and their later sale are separate tax events. The reward may be ordinary income when received. A later sale or exchange can create a capital gain or loss. Our crypto mining taxes guide explains the income side.
A bona fide gift is not automatically a Form 8949 disposition for the donor. Gift-tax reporting and the recipient's basis are separate issues. Form 1099-DA also does not determine whether a transaction is reportable.
For details on how the resulting gain may be taxed, see our cryptocurrency tax rate guide.
What Changed for Form 8949 and Form 1099-DA?
Digital asset brokers began reporting gross proceeds for certain transactions on Form 1099-DA for the 2025 reporting year. For sales after 2025, brokers generally must report basis for covered digital assets. A covered digital asset generally must have been acquired after 2025 and held in the same custodial account until the broker handled the sale. A 2025 Form 1099-DA may therefore show proceeds without showing basis.
The 2025 Form 8949 also introduced digital-asset-specific categories. Use boxes G, H, and I for short-term digital asset transactions and boxes J, K, and L for long-term transactions.
2025 Form 8949 digital asset box guide
| Form 1099-DA status | Short-term | Long-term |
| Basis reported to the IRS | G | J |
| Basis not reported to the IRS | H | K |
| No Form 1099-DA received | I | L |
Use the applicable checkbox shown on Form 1099-DA when it agrees with your records. If the broker did not know your holding period or basis, use your records to determine the correct treatment. Form 1099-DA does not replace transaction histories from every exchange and wallet you used.
Step-by-Step Guide to Filling Out Form 8949 for Cryptocurrency
Step 1: Identify Your Cryptocurrency Disposals
Start with every centralized exchange, hosted wallet, and self-custody wallet you used during the year. Identify sales for cash, crypto-to-crypto exchanges, purchases made with cryptocurrency, and applicable NFT disposals.
Match transfers between wallets or accounts that you own so they are not misclassified as sales. Keep the associated network fees in your records because paying a fee with digital assets can itself create a reportable transaction. Donating crypto directly to a qualified charity is generally not a taxable disposal, and for assets held more than a year it can also avoid the gain entirely. Reportable disposals generally require transaction-level information unless an IRS exception applies.
Step 2: Gather and Reconcile Your Transaction Records
For each disposal, gather:
- Asset name and number of units
- Acquisition date and time
- Disposal date and time
- Proceeds or fair market value in U.S. dollars
- Cost or other basis
- Transaction fees
- Source exchange, wallet, or platform
Download exchange CSV files, wallet histories, and applicable Forms 1099-DA. Include prior-year records when an asset's basis originated outside the broker that handled the sale.
If an exchange has shut down or you can no longer download your history, your IRS online account will show the information returns filed under your SSN.
Reconcile the records before you touch the form. Match transfers, remove duplicate imports, compare broker-reported proceeds with Form 1099-DA, and flag missing or zero-basis entries. A clean transaction history should show where each disposed unit came from and how its basis was determined.
Step 3: Categorize Transactions as Short-Term or Long-Term
Use the acquisition and disposal dates to determine the holding period. Start counting on the day after you acquired the asset and include the day you disposed of it.
An asset held for one year or less is generally short-term. An asset held for more than one year is generally long-term. The classification determines whether the transaction belongs in Part I or Part II of Form 8949.
Step 4: Select the Correct Reporting Option
Apply the 2025 box guide above. Use G, H, or I for short-term transactions and J, K, or L for long-term transactions. The choice depends on whether you received Form 1099-DA and whether the statement says basis was reported to the IRS. Each reporting category needs a separate Part I or Part II.
Do not use the older C and F boxes for 2025 digital asset transactions. If you are preparing a return for a different year, use that year's Form 8949 and instructions rather than applying the 2025 categories automatically.
Step 5: Report Each Disposal on Form 8949
Map your reconciled records to columns (a) through (h):
| Column | What to enter |
| (a) | Asset description and units disposed, plus the sale transaction ID when available |
| (b) | Date acquired |
| (c) | Date sold or disposed of |
| (d) | Proceeds shown on Form 1099-DA, or net proceeds when no form applies |
| (e) | Cost or other basis |
| (f) | Applicable adjustment code |
| (g) | Adjustment amount |
| (h) | Gain or loss after adjustments |
If you received Form 1099-DA, report the proceeds shown on the form in column (d).
When basis was not reported to the IRS, enter your correct basis directly in column (e). When the form says basis was reported to the IRS and that figure is wrong, enter the reported basis in column (e) and correct it using the adjustment code in column (f) and the adjustment amount in column (g).
If a broker's figures are wrong, follow the IRS correction instructions and keep records supporting the change.
NFT treatment depends on the asset and the transaction. Some NFTs may be subject to special collectible rules, but that does not mean every NFT belongs on a separate type of Form 8949. Review the facts before applying special treatment.
Step 6: Transfer Your Totals to Schedule D
Subtotal each checked Form 8949 category separately. Transfer the short-term and long-term totals to the corresponding Schedule D lines. Schedule D combines those amounts with other capital transactions and any applicable capital loss carryover.
If the form cannot hold every transaction, you may attach a statement with the same information in a similar format and enter the combined totals on Form 8949. Certain transactions with basis reported to the IRS and no adjustments may go directly on Schedule D. Follow the current Form 8949 and e-file instructions
Free checklist · Seven steps
The Form 8949 Crypto Tax Checklist
This article walks the six steps. The checklist is what you work from while your exchange exports are open in front of you.
- A box G through L reference table, so you pick the right digital asset box by holding period, Form 1099-DA, and whether basis was reported
- Why most 2025 Forms 1099-DA fall under box H or box K, and when G and J start to apply
- Column-by-column entries for (a) through (h), including when adjustment code B belongs in column (f)
- The reconciliation pass that catches duplicate CSV and API imports and unexplained zero-basis units
- Why 2025 and later means tracking basis by wallet or account, not across combined holdings
Fillable PDF · works printed · no cost
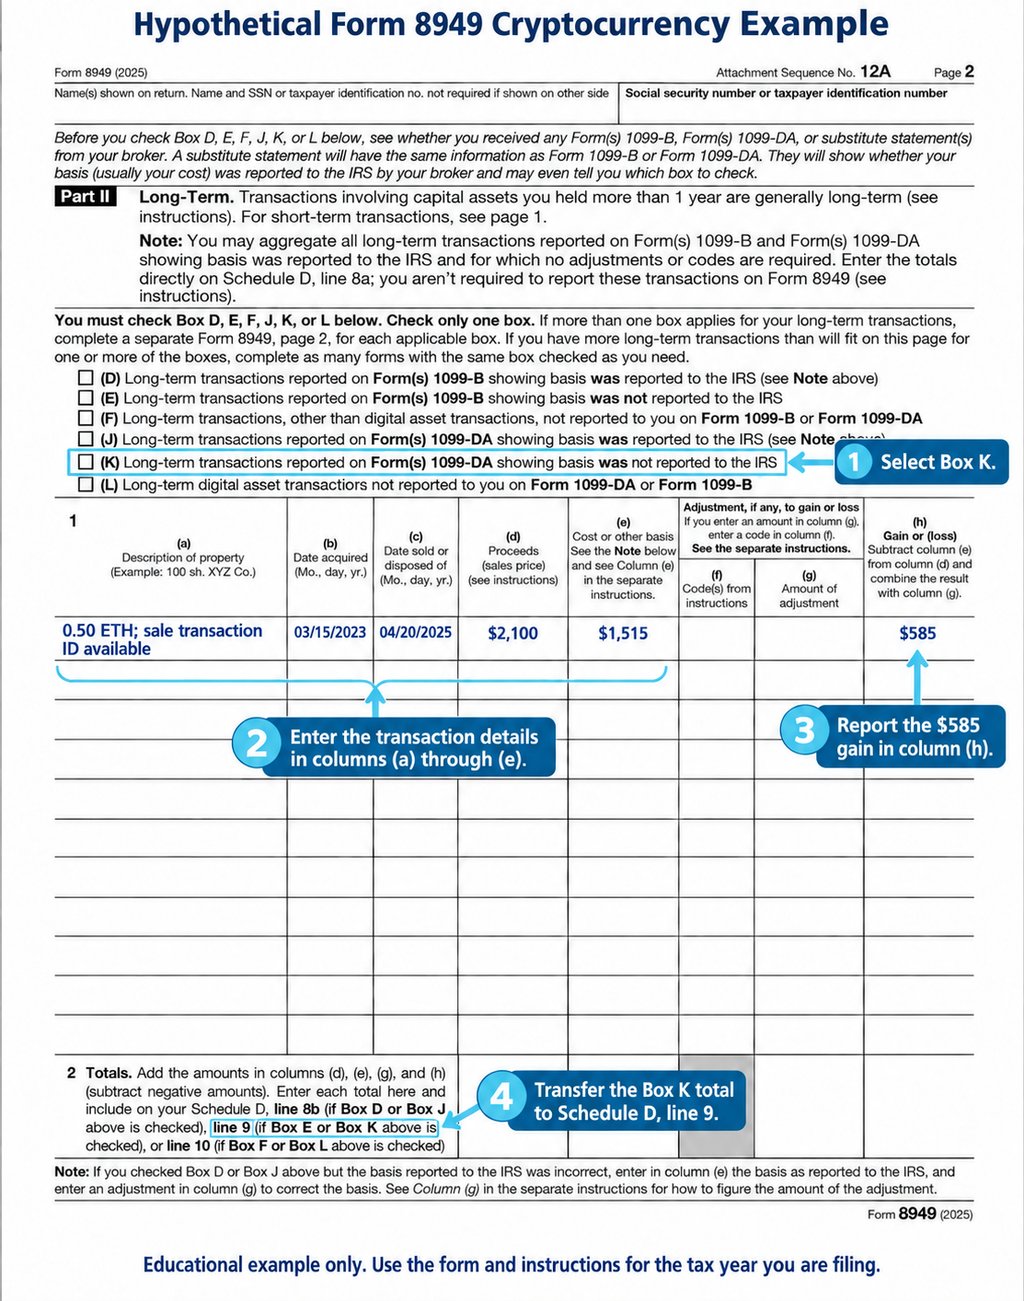
Form 8949 Cryptocurrency Example
Assume you bought 0.50 ETH for $1,500, paid a $15 acquisition fee, and sold it more than one year later for $2,100. The broker reported proceeds but not basis.
| Form field | Example entry |
| Box K | Checked |
| (a) | 0.50 ETH (sale transaction ID, if available) |
| (b) | March 15, 2023 |
| (c) | April 20, 2025 |
| (d) | $2,100 |
| (e) | $1,515 |
| (f) and (g) | Blank; no adjustment is required in this example |
| (h) | $585 gain |
The result is a $585 long-term capital gain. Report it in Part II with box K checked, then include it in the box K total transferred to line 9 of the 2025 Schedule D.
This example assumes no selling fee or adjustment. Resolve any difference between the broker form and your records before filing.
How to Calculate Your Crypto Gain or Loss
Form 8949 calculates a realized capital gain or loss, not your complete cryptocurrency tax bill. The basic calculation is proceeds minus adjusted basis.
Your basis generally starts with the U.S. dollar cost of the digital asset plus acquisition costs such as transaction fees and commissions. For a crypto-to-crypto trade, use the U.S. dollar fair market value of what you received at the time of disposal as the starting point for proceeds. Selling costs may reduce net proceeds when no broker statement applies. If you received Form 1099-DA, follow the form instructions for reporting broker figures and any required adjustments.
Receiving cryptocurrency for services, mining, or staking can create ordinary income. That income amount may establish a basis in the asset. A later sale or exchange is a separate event that can create a capital gain or loss. Gifts, inherited assets, business inventory, personal-use losses, and some NFT transactions follow additional rules.
How Do You Handle Multiple Wallets, Missing Basis, or Too Many Transactions?
When you hold the same cryptocurrency across several wallets or accounts, you have to identify which units were disposed of within the relevant wallet or account. If you bought those units at different prices, that identification affects the gain you report. Under the specific identification rules, the identification has to be made by the time of the sale or transfer and supported by records showing each unit's acquisition date and basis.
Without that support, the default rule treats the earliest-acquired units as sold first (FIFO). Changing a software setting at filing time does not necessarily satisfy the requirement, and the IRS applies different broker identification rules for 2025 than for sales after 2025.
For transferred-in assets, trace each disposal back to the original acquisition using transaction hashes, wallet addresses, timestamps, exchange CSVs, and prior-year records. When you correct an import or manually add basis, keep the source record and a note explaining the change.
For a high volume of transactions, use software or a structured transaction statement that preserves the required Form 8949 fields. The current IRS instructions allow attached statements in a similar format, but the statement must contain the transaction details. Summary totals alone are not enough unless a specific exception applies.
How Should You Choose Crypto Cost-Basis Software for Form 8949?
There is no universal best cost-basis solution for every cryptocurrency or NFT investor. Evaluate whether the software can:
- Import every exchange and wallet you use
- Match transfers without treating them as sales
- Track basis separately by wallet or account when required
- Support specific identification and other permitted basis methods, and record when each identification was made rather than only at export
- Handle DeFi and NFT transactions in your records
- Flag missing basis, duplicate imports, and unmatched transfers
- Reconcile proceeds and basis information with Form 1099-DA
- Export transaction details, Form 8949 categories, and Schedule D totals
- Preserve an audit trail and provide access for your tax professional
Review unresolved warnings and spot-check transactions before relying on any software-generated report. No tool can determine every fact behind complex transfers, DeFi activity, gifts, or inherited assets. The report is only as reliable as its source records and classifications.
What Should a Crypto Tax Report Include?
A complete crypto tax report should include transaction-level Form 8949 data, separate subtotals for each reporting box, totals that tie to Schedule D, and a realized gain-and-loss report. It should also preserve the underlying exchange and wallet histories used to determine basis.
Keep the original CSV files, wallet exports, Forms 1099-DA, software settings, reconciliation notes, and documentation for manual adjustments. A generated PDF alone may not explain how the software matched transfers or resolved missing information.
Common Mistakes to Avoid When Filing Form 8949
Before filing, check for:
- Omitted sales, swaps, purchases, and other disposals
- Wallet transfers incorrectly treated as sales
- Missing or unsupported cost basis
- Form 1099-DA proceeds that do not reconcile to the return
- Inconsistent treatment of acquisition and selling fees
- Incorrect holding periods or reporting boxes
- Adjustments without supporting records
- Form 8949 totals that do not agree with Schedule D
Unreported disposals and unexplained zero-basis entries are the kind of thing that invites a closer look, so it helps to know what draws IRS attention.
When Should You Ask a Crypto Tax Professional for Help?
Professional review makes sense when your records contain unresolved missing basis, conflicting broker forms, many wallets or exchanges, DeFi or NFT transactions, inherited or gifted assets, prior-year omissions, business activity, or adjustments you do not know how to report.
If you have missing cost basis, conflicting Forms 1099-DA, or multiple wallets, our cryptocurrency tax services team can discuss your filing needs with you.
Our process starts with transaction-data reconciliation, followed by CPA review and tax preparation support. CMP supports clients nationwide through remote engagement.
When you get in touch, mention the tax year, the platforms you used, and the issues you have not been able to resolve.
Frequently Asked Questions About Form 8949 for Cryptocurrency
Do I need Form 1099-DA to report cryptocurrency on Form 8949?
No. Report applicable sales and exchanges even without Form 1099-DA. Use your records and select the box for transactions without the form.
Can I summarize crypto transactions instead of listing every transaction?
Sometimes. Qualifying transactions may go directly on Schedule D. You may also attach a statement with the same details as Form 8949 in a similar format. Follow the current IRS instructions.
Do transfers between my own crypto wallets go on Form 8949?
Generally, no. Moving an asset between wallets or accounts you own does not change ownership. However, paying a network or transfer fee with cryptocurrency can create a separate digital asset transaction.
What should I do if I cannot find the acquisition date or cost basis?
Trace it through your own records before accepting a zero basis. Do not invent a date or amount. Document any unresolved gap and ask a tax professional how to report it.
If you already filed and the basis turns up later, or a corrected Form 1099-DA arrives, you can file an amended return rather than leaving the error in place.
Do cryptocurrency and NFT losses go on Form 8949?
Capital losses from sales or exchanges of investment cryptocurrency and NFTs generally go on Form 8949. Losses on personal-use property are generally not deductible, and NFT treatment depends on the asset and transaction.
How long should I keep cryptocurrency transaction records?
Keep records that support basis, proceeds, holding period, and other reported positions. You may need to keep basis records while you hold the asset and through the applicable limitations period after disposal. Confirm the period with your tax advisor.
Final Thoughts on Filing Form 8949 for Cryptocurrency
Straightforward transactions can be manageable when your records are complete and reconciled. Missing basis, multiple wallets, broker mismatches, and complex digital asset activity deserve closer review. If that describes your situation, contact us and mention the tax year, the platforms you used, and the issues you have not resolved.
Talk to a CPA
Have a crypto tax question you can't answer from a guide?
Missing basis, wallets that won't reconcile, and a Form 1099-DA that disagrees with your records are the cases worth handing to someone. CMP's crypto tax team works with investors, traders, miners, and businesses nationwide.
Request a Crypto Tax ConsultationTakes less than 30 seconds. No cost, no obligation.